Key Takeaways
- Compare the complete ownership cost, not simply the asking price.
- Measure daily life factors such as commute time, parking, walkability, privacy, and access to services.
- Review the condition, disclosures, permits, and insurance before deciding how much risk to include in an offer.
- Use recent, closely matched sales rather than broad Bay Area averages to assess value.
- Set a walk-away price before competition, or a memorable view makes the decision emotional.
Table Of Contents
- Introduction
- Why These Markets Feel Different
- Start With Your Priorities
- Compare the Total Cost
- Review Property Condition
- Measure Location and Commute
- Study Market Evidence
- Build a Home Scorecard
- Prepare a Smart Offer
Buying on either side of the Golden Gate can involve very different trade-offs. San Francisco offers dense neighborhood choices, varied building types, and block-by-block changes in transit, noise, sunshine, and parking. Marin County can offer more space, greenery, and a different pace, while raising questions about driving routes, lot maintenance, insurance, and the distance to everyday errands.
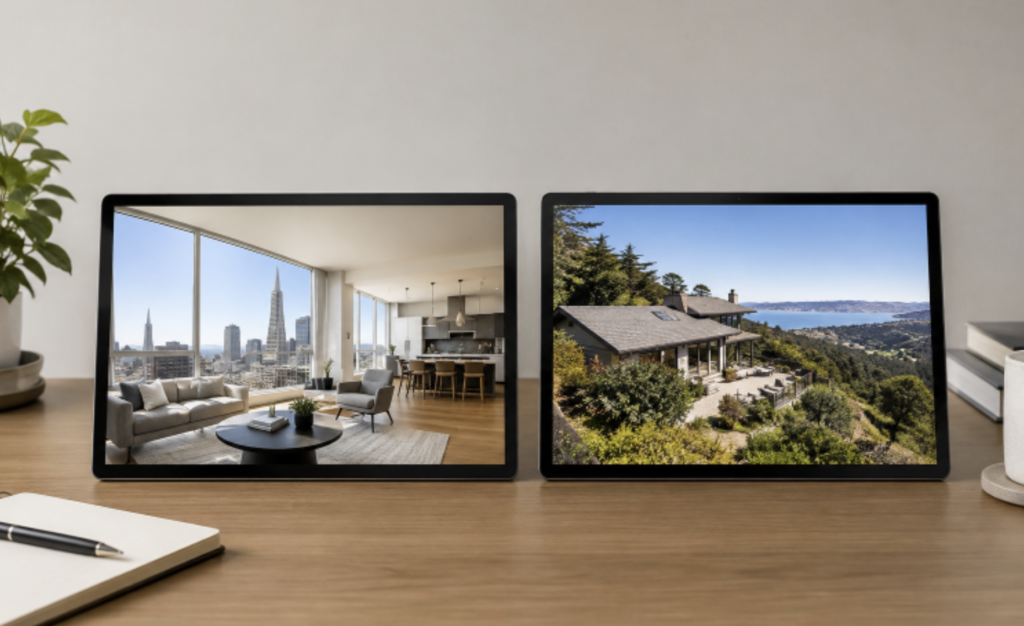
For buyers weighing both markets, San Francisco real estate experts Applegarth + Warrin are part of Warrin Team Real Estate, a residential team focused on homes in San Francisco and Marin County. Their website covers local property searches, listings, market insights, and buyer and seller services across communities, including San Francisco, Belvedere-Tiburon, Sausalito, Mill Valley, Ross, and the surrounding Marin area. That local perspective matters when a condominium near a transit line and a hillside home with outdoor space may carry very different costs and responsibilities.
Why These Markets Feel Different
San Francisco and Marin County sit close together geographically, but homes serve different routines. A San Francisco buyer may prioritize proximity to work, restaurants, parks, transit, and cultural activity. A Marin buyer may put more weight on usable outdoor space, school routes, a quieter setting, or access to trails and waterfront areas. Neither setting is automatically better. The right choice depends on how the home supports the life you expect to live after closing.
Property types also vary. In San Francisco, buyers may compare condominiums, TICs, flats, single-family homes, and buildings with shared systems or homeowner association obligations. In Marin, the comparison may involve older homes, sloped lots, private roads, drainage, retaining walls, vegetation management, or septic and well considerations in certain locations. Broad market headlines cannot replace a property-specific review.
Start With Your Priorities
Create a written brief before the first serious tour. It helps prevent a striking kitchen, dramatic view, or polished staging from overshadowing practical needs.
A Useful Buyer Exercise
- Write down five must-have features, such as a home office, garage, flat walk to shops, yard, or elevator.
- List five preferences that would improve life but are not essential.
- Identify three deal breakers, including an unacceptable commute, major deferred maintenance, or inadequate space.
- Rank each item by lifestyle value, cost, and difficulty of changing it later.
Think several years ahead. Consider children, guests, aging relatives, pets, remote work, storage, and the possibility that a future buyer may value the same features you do.
Compare the Total Cost
Two similarly priced homes can have meaningfully different monthly obligations. Build a comparison that includes mortgage principal and interest, property taxes, homeowners’ insurance, HOA dues, utilities, expected maintenance, parking, bridge tolls, fuel, and transit costs.
Also reserve money for one-time expenses. California property purchases can trigger a reassessment and a supplemental tax bill in addition to the regular annual bill, so buyers should understand how supplemental assessments can follow a change in ownership before treating the seller’s tax bill as their own future cost.
Simple Cost Formula
Estimated monthly cost = mortgage + taxes + insurance + HOA + utilities + maintenance reserve + transportation.
Run the estimate over at least three years. A lower purchase price may lose its advantage if the home needs immediate work, requires a long commute, or carries greater insurance and upkeep demands.
Review Property Condition
Condition should shape both value and offer terms. Read disclosures carefully, then pair them with inspections, contractor estimates, and public records. Focus on the roof, foundation, drainage, retaining walls, electrical capacity, plumbing, heating, windows, moisture control, and earthquake-related improvements.
For San Francisco property, buyers can use the city’s permit and complaint tracking system to research permit history by address. Match that history against visible improvements and seller disclosures. In any location, ask whether renovations were permitted, whether final approvals were obtained, and whether work changed the home’s future maintenance needs.
For condominiums, review the HOA budget, reserves, meeting minutes, insurance, rental rules, and any discussion of special assessments. Shared ownership can simplify certain exterior maintenance, but it also makes the association’s financial health part of the purchase decision.
Measure Location and Commute
Visit more than once. A quiet Saturday open house may not reveal weekday traffic, school pickup activity, nearby nightlife, fog patterns, or parking pressure. Test the route to work or school at the times you would actually travel. Walk from the front door to transit, groceries, parks, and other destinations that matter to your household.
In San Francisco, evaluate the block as closely as the neighborhood. Street grade, loading zones, bus routes, construction activity, and building density can quickly change the experience. In Marin, look carefully at driving routes, road access, slope, drainage, wildfire preparation, and the distance to daily services. Obtain insurance quotes early, especially when a home’s site or location could affect availability, deductibles, or coverage terms.
Study Market Evidence
Use recent comparable sales that resemble the home in location, condition, size, layout, lot, parking, view, and building type. Review original list price, final sale price, days on market, price changes, and current competing inventory. A sale from a different neighborhood, school area, or condominium building may provide useful background, but it is not a direct substitute for a close match.
Ask why each comparable matters. A renovated home may set a higher benchmark, while a property with deferred maintenance may reveal how buyers discount repair risk. This analysis is also useful when deciding whether an offer should include protections for inspection, financing, or appraisal.
Build a Home Scorecard
Score each finalist from one to five, then apply weights based on your priorities:
- Location, 25%: Does the setting support routines and long-term plans?
- Financial fit, 20%: Can the full cost fit comfortably with reserves?
- Property condition, 20%: What needs attention now and soon?
- Lifestyle fit, 15%: Does the layout work for work, rest, storage, and guests?
- Resale potential, 10%: Will future buyers see clear strengths?
- Offer position, 10%: Does the price align with evidence and competition?
Prepare a Smart Offer
A strong offer is not always the highest offer. It should reflect the home’s condition, the quality of the comparable sales, your financing, and the risks you are willing to accept. Before writing, confirm cash reserves, estimate immediate repairs, decide which contingencies are essential, and set a firm maximum price.
The best comparison is not based on square footage or list price alone. By weighing ownership costs, condition, daily logistics, and evidence from closely matched homes, buyers can choose between San Francisco and Marin County with more clarity and make an offer that fits both the property and their future.